Industry Education
Oxford Underwrites a Tenant's AI Exposure Before Buying the Building. What Should a Tenant-Rep Broker Underwrite Before a Renewal?
By Casey Krueger, Founder & CEO, BrokerHQ · Published September 27, 2026 · 7 min read
What did Oxford actually say it's doing?
Ankit Bhatt, Head of US Investments at Oxford Properties, told the AI for CRE Collective in mid-September that his team now factors AI exposure directly into how it underwrites office acquisitions. "We take that into account in our underwriting," Bhatt said, describing a process that looks past a building's current rent roll to ask which tenants are positioned to thrive as AI reshapes their businesses and which are exposed to contraction.
The targets are Boston, New York, and San Francisco, all markets with heavy concentrations of technology and AI-adjacent employers. The context is real money: Oxford closed on One Marina Park Drive in Boston's Seaport District in August for $435 million, a 500,000-square-foot Class A tower that's 99% leased. It's the firm's first stabilized US office acquisition in nearly a decade, part of roughly $2 billion Oxford has put back into office globally since early 2025, after pulling about $14 billion out of the sector between 2018 and 2022.
AI exposure sits alongside the underwriting factors that have always mattered: lease terms, credit quality, location, building quality, market fundamentals. What's new is treating a tenant's exposure to AI-driven business change as its own line item, worth asking about directly rather than assuming it washes out in the credit score. A landlord is now underwriting a tenant's future, not just its credit history.
Why would a landlord care what happens to a tenant's business after AI, not just whether the tenant pays rent on time?
Because credit quality today is a photograph, and a ten-year office bet is a bet on the next ten years. A tenant can be investment-grade this quarter and still be running a business model AI is actively hollowing out. Oxford's framing treats that as underwritable risk rather than an externality: not "will this tenant renew," but "will this tenant's business still need this much space, staffed this way, by the time the option comes up."
That's a landlord asking a forward-looking question about an occupier's business, using tools a tenant-rep broker doesn't have: audited financials, deep sector research, portfolio-level pattern matching across hundreds of similar tenants. A broker working one client's renewal will never out-resource that.
What's the mirror-image question a tenant-rep broker should actually be asking?
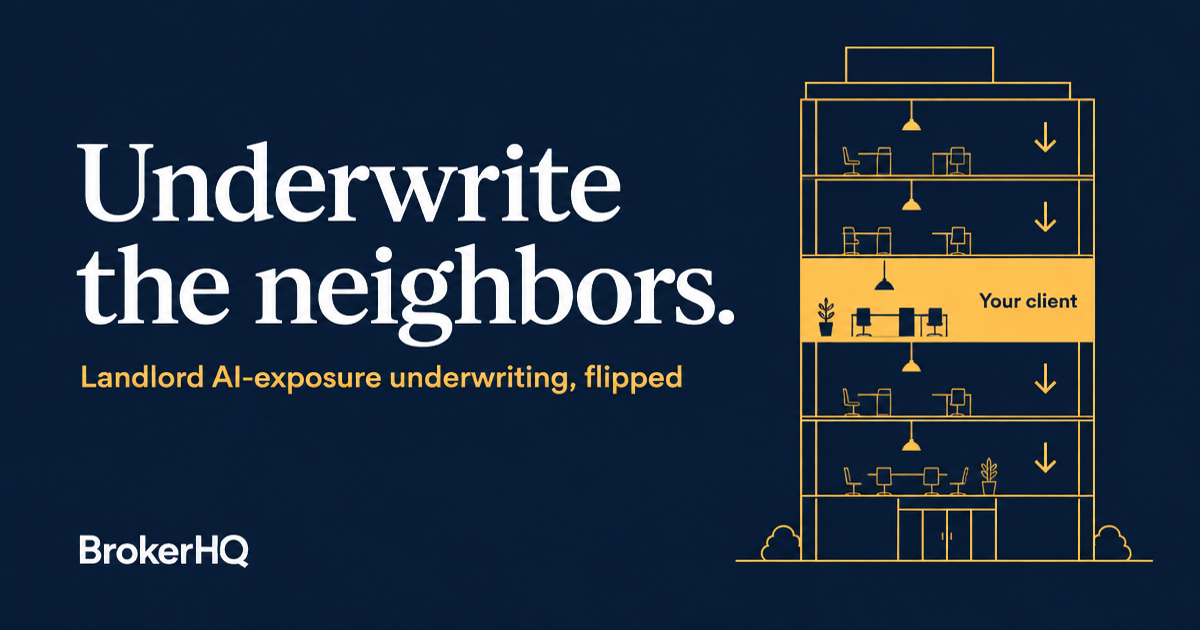
Not "is my client exposed to AI." The client already knows their own business better than any outside underwriter ever will; that's not the gap. The lens Oxford applies to a tenant, a broker can apply to the tenant's neighbors. The gap is on the other side of the wall. When a broker walks a client into a building, whether for a renewal in place or a new lease, the client is one tenant in a portfolio of other tenants nobody is watching on the broker's behalf.
A rent roll is a list of names. It isn't a list of risks. Every one of those other names is a company with its own headcount trend, its own funding status, its own exposure to whatever is reshaping its sector. If three of the five other floors in a building are leased to companies quietly contracting, that building has space coming back before it has a listing for it, and that's exactly the kind of leverage a broker wants walking into a renewal conversation: softening demand in the building translates into concession room, TI dollars, and a landlord more willing to negotiate term.
Space coming back is a fact before it's a listing. By the time a sublease hits the market, every broker in the submarket already knows about it and the leverage is gone. The value is in seeing it early, which means doing to the neighbors roughly what Oxford does to the whole building: ask which of them look like they're shrinking, and why.
How would a broker actually build this without Oxford's balance sheet?
Oxford has audited financials and analyst headcount most tenant-rep desks will never get. But the individual signals a broker can watch on a public-records budget aren't exotic, they're the same building blocks that make company-level tracking possible at all: headcount change visible in job postings and WARN notices, business license status and Secretary of State filings for the named tenants in a building, active sublease listings tied to the address, and permit activity that signals either recommitment or an impending move. None of these alone proves a company is contracting. Stacked across every named tenant in a building, they turn a rent roll into something closer to a stress map.
Nobody underwrites the tenant-rep side of AI exposure risk. Landlords are starting to, because a bad tenant mix is now a line item on their acquisition model. A broker who builds even a rough version of the same view, three or four public signals per neighbor rather than Oxford's full underwriting stack, walks into a renewal with information the other side of the table doesn't expect a tenant rep to have.
Isn't this just speculation dressed up as diligence?
It's a fair challenge, and it deserves an honest answer rather than a dismissal. Oxford's underwriters have access to information a tenant-rep broker never will: management conversations, audited financials, sector research built over hundreds of deals. Public-records signals on a handful of neighboring tenants are a much thinner evidence base, and treating three job postings and a WARN filing as proof that a neighbor is about to give back space would be overclaiming exactly the kind of confidence this playbook warns against elsewhere.
The honest use of this approach is as a prioritization tool, not a verdict. A building where two or three named tenants show real contraction signals is a building worth a closer look and a more assertive negotiating posture. A building with no visible signals isn't necessarily safe, it's just unmeasured. The output should read like a short list of things to check before the LOI, not a confident forecast printed into a client memo.
BrokerHQ's view
This is the same argument underneath almost everything in this playbook: the useful unit of intelligence in tenant representation usually isn't the client, it's everyone around the client. Oxford is proving that out on the landlord side with money most brokerages will never have. The tenant-rep version doesn't need Oxford's balance sheet, it needs the discipline to ask the question about the building instead of just the client, and a place to keep the answer that doesn't live in one broker's head.
What can a broker check on a building this week?
Before the next renewal conversation or new-deal tour, four things cost nothing but time:
Pull the public business-license or Secretary of State status for every named tenant on the rent roll you can see, and flag anything showing recent registered-agent changes, inactive status, or a name that no longer matches current signage.
Search for active sublease listings tied to the building's address on the major listing platforms, even ones outside your usual search radius; a sublease that isn't yet on your radar is still leverage once you know it exists.
Check the WARN notice database for the submarket zip code for the trailing 90 days; a notice tied to a building tenant is close to a confirmed signal, not a guess.
Set a date to re-check the same building 30 days before your LOI is due, and note what changed. If nothing did, you've lost nothing. If something did, you found it before the other side of the table volunteered it.
Frequently asked questions
What did Oxford actually say it's doing?
Oxford Properties now factors a tenant's AI exposure directly into how it underwrites US office acquisitions, alongside lease terms, credit quality, location, and building quality.
Why would a landlord care what happens to a tenant's business after AI?
Because credit quality today is a snapshot, and a ten-year office bet is a bet on the next ten years of a tenant's business model.
What's the mirror-image question a tenant-rep broker should ask?
Not whether their own client is exposed to AI, but whether the building's other tenants show signs of contraction that translate into negotiating leverage.
How would a broker build this without Oxford's balance sheet?
By stacking public-records signals, such as headcount change, business license status, sublease listings, and permit activity, across every named tenant in a building.
What can a broker check on a building this week?
Business-license and Secretary of State status for named tenants, active sublease listings tied to the address, WARN notices in the submarket, and a scheduled re-check before the LOI is due.
Sources
- Ankit Bhatt (Oxford Properties), quoted in "Oxford adds AI exposure to office underwriting," AI for CRE Collective, Sep 15 2026. (third-party)
- One Marina Park Drive acquisition figures ($435M, 500,000 sq ft, 99% leased), same source. (third-party)
- Oxford's ~$2B global office redeployment since 2025 and ~$14B recycled 2018-2022, same source. (third-party)
Liked this?
The weekly Seattle CRE Brief brings the same kind of read to your inbox every Friday. Subscribe, it's free.
See sourced intelligence on your market
Every claim linked back to the filing or record it came from.